What to Watch Next: Key Milestones Toward 2027 and 2028
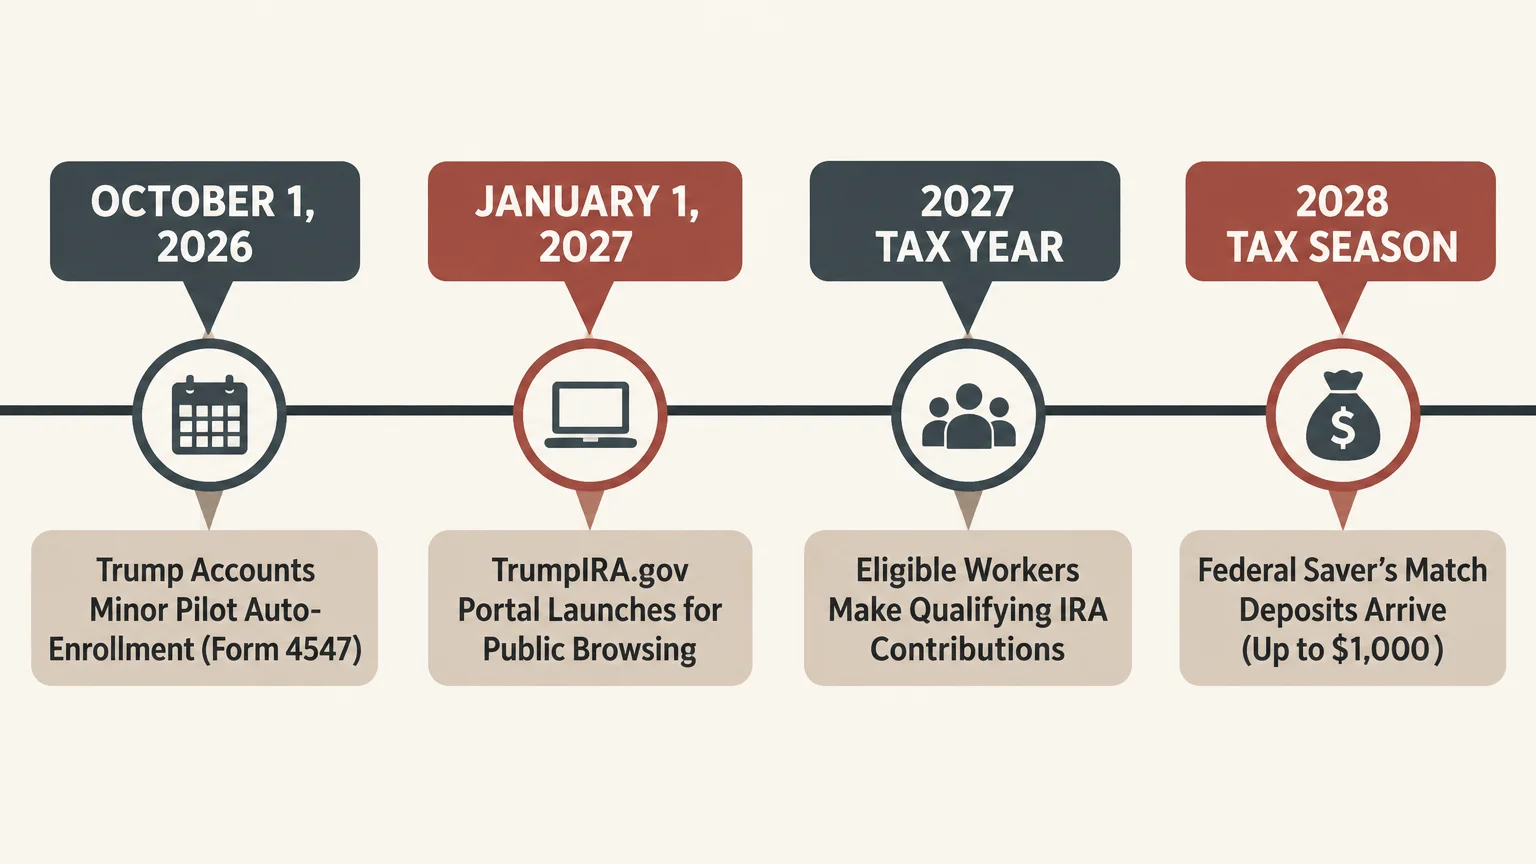
The first major test arrives on January 1, 2027, when Treasury is scheduled to open TrumpIRA.gov to the public. Watch which major brokerages meet the 0.15 percent fee cap, waive all minimums, and commit to accepting federal matching deposits.
On the regulatory front, look for the IRS to publish formal proposed regulations following Notice 2026-48 alongside a draft of Form 8880-A. Those documents will determine whether Roth savers can use a streamlined conduit Traditional IRA without unexpected tax penalties.
On Capitol Hill, track whether lawmakers advance Sen. Wyden’s Saver’s Match Enhancement Act of 2026 or debate Treasury’s forthcoming bill to codify TrumpIRA.gov. Expanding the phase-out thresholds before 2028 inflation indexing begins would pull millions of additional middle-income households into the program.
You can prepare now by checking your expected 2027 filing status and Modified Adjusted Gross Income against the statutory brackets. Ask your human resources department whether your workplace retirement plan intends to accept Federal Saver’s Match deposits, or plan to open a low-fee Traditional IRA early in 2027.
Automating even $50 to $165 per month starting in January 2027 positions you to capture matching federal dollars without scrambling at year-end. Staying alert to IRS filing rules ensures your contributions translate into real retirement security when payouts begin in 2028.