Eligible low- and moderate-income workers can claim up to $1,000 a year in federal retirement matching funds starting with 2027 contributions, though deposits arrive in 2028. President Donald Trump spotlighted this benefit through an April 30, 2026 executive order establishing TrumpIRA.gov.
However, Executive Order 14403 does not create a government-run retirement plan or fund a new match. Congress enacted the Federal Saver’s Match in December 2022 under the SECURE 2.0 Act, and Trump’s order connects that law to private accounts.
Knowing the income caps, payout rules, and political strategy behind this rollout helps you claim every dollar you qualify for.
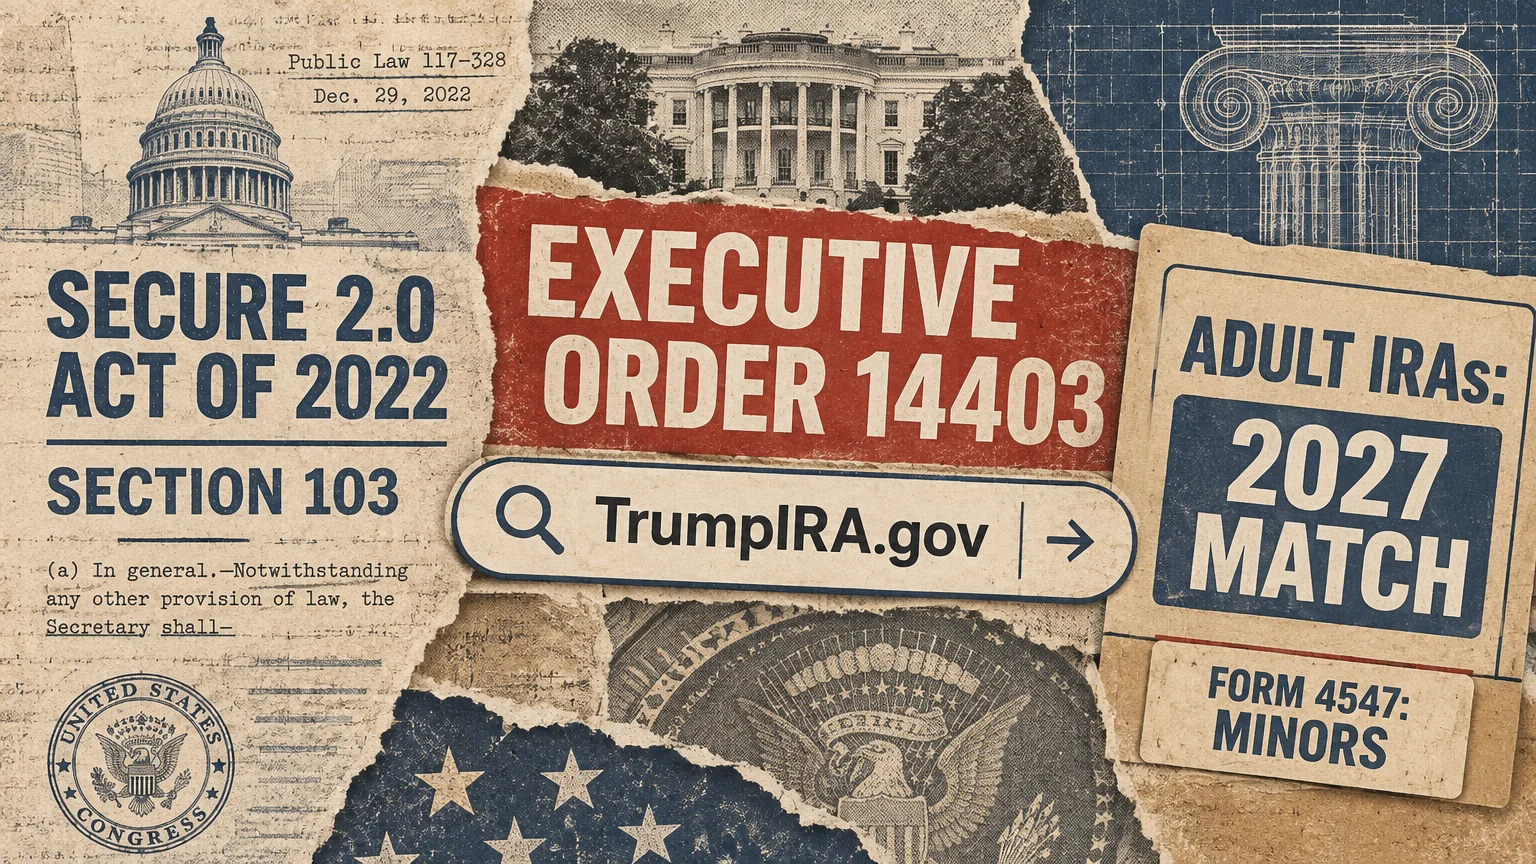
The Flashpoint: Executive Order 14403 and the TrumpIRA.gov Launch
Following remarks in his February 24, 2026 State of the Union address, President Trump signed Executive Order 14403 on April 30, 2026. The directive instructs the U.S. Department of the Treasury to launch TrumpIRA.gov by January 1, 2027.
Administered by Treasury alongside the Internal Revenue Service and the Department of Labor, the portal does not operate a public pension or federal investment fund. Instead, it serves as a free informational marketplace where you can browse and compare private-sector Individual Retirement Accounts.
The platform targets workers who lack access to employer-sponsored plans, including independent contractors, part-time workers, small-business employees, and the self-employed. You use the website to review participating providers before opening a standard private account.
To earn placement on TrumpIRA.gov, private IRAs must cap net expense ratios at 0.15 percent annually, or 15 basis points. Participating accounts also cannot require a minimum balance or a minimum contribution.
Every listed IRA must offer diversified, index-based, or lifecycle investments such as target-date funds alongside principal-protection options. Providers must also agree to accept incoming Federal Saver’s Match deposits from the federal government.
White House messaging frames TrumpIRA.gov as a signature executive initiative, yet the underlying $1,000 match comes from an earlier bipartisan law. Executive Order 14403 builds its marketing platform around a statutory benefit Congress passed four years earlier.
Specifically, the matching dollars flow from Section 103 of Division T of the SECURE 2.0 Act of 2022, codified at Internal Revenue Code Section 6433. President Joe Biden signed that legislation into law on December 29, 2022, as tracked on Congress.gov.
You should also avoid confusing TrumpIRA.gov with a separate federal program called Trump Accounts. Created under the Working Families Tax Cuts, Trump Accounts operate as custodial IRAs specifically for minors.
Treasury began auto-enrolling eligible children into Trump Accounts on October 1, 2026. Under that pilot program, U.S. citizen children born between January 1, 2025, and December 31, 2028, may qualify for a one-time $1,000 federal contribution elected via Form 4547.
By contrast, TrumpIRA.gov pairs adult workers with low-fee private IRAs to capture an ongoing annual match. Keeping those two programs separate prevents costly filing mistakes when tax season arrives.